Leveraged ETFs as an Implementation Tool for Family Offices
Abstract
Family offices often see an opportunity in public markets at a moment when their liquid capital is already committed to private investments, capital calls, taxes or operating needs. This paper examines leveraged exchange-traded funds as one way to add equity exposure without new cash, by restating part of an existing allocation at higher exposure. It explains the three mechanical features that separate appropriate uses from inappropriate ones (capital efficiency, the daily reset and path dependence, and embedded financing), compares leveraged ETFs with index futures, margin, options and total return swaps, and describes where each fits. It closes with six questions a family office should answer before any exposure goes on, and with the risks that remain however well a position is managed. It does not argue that leverage belongs in every portfolio, or that leveraged ETFs are the right vehicle for every purpose.
Nothing in this white paper constitutes investment, tax, legal, or accounting advice. The discussion of leveraged exchange-traded funds and other ways to add equity exposure is a general educational summary only, and individual results depend on specific facts and circumstances. Readers should consult their own qualified advisers before acting on anything described herein, and should not rely on this white paper as a substitute for such advice.
The Capacity Problem
Most discussions of leveraged ETFs start with the product. This one starts with a portfolio problem that family offices know well: an opportunity appears in public markets, and there is no capital available to act on it.
A family office balance sheet is rarely idle. Capital is deployed across public equities, private equity, private credit, real estate, and other alternatives, and much of what remains liquid is already spoken for by capital calls, distributions, taxes, or operating needs. When public equities pull back in an otherwise healthy market, the office may conclude that exposure should rise and still have no practical way to raise it.
Those pullbacks are not rare. Since 1928, the S&P 500 has had 47 declines of 5–10% that did not become a 20% bear market; median time to recover the prior high was 34 trading days.1
There are four ways to resolve the constraint: hold cash in advance, sell something else, borrow, or use an instrument with leverage built in. Cash held in advance carries a permanent opportunity cost for a temporary need. Selling another position moves exposure around the balance sheet without adding to it. That leaves borrowing and embedded leverage, and within those, the choice of vehicle matters as much as the decision to add exposure.
This paper explains how leveraged ETFs work as one such vehicle, compares them with the alternatives, and sets out the governance questions a family office should answer before using any of them. It does not argue that leverage belongs in every portfolio, or that leveraged ETFs are the right vehicle for every purpose.
How Leveraged ETFs Actually Work
Leveraged ETFs have a reputation, much of it earned by investors who used them for purposes they were not designed for. Three mechanical features account for most of the difference between an appropriate use and an inappropriate one.
Capital efficiency
A leveraged ETF delivers a multiple of an index’s daily return per dollar invested. That changes the question from “where do we find new cash?” to “how much of an existing allocation can be restated at higher exposure?”
Consider a portfolio with 100% equity exposure. It sells 7.5% of its unlevered index position and buys 7.5% of a 3x fund on the same index. Equity exposure rises to 115% (92.5% × 1 + 7.5% × 3) with no new capital. Restating 20% of the portfolio the same way takes exposure to 140%. The rest of the portfolio is unchanged, and the incremental exposure sits in a single position that can be sized, monitored, and sold.
The efficiency works in both directions. In that 140% case, a 10% index decline costs the 20% sleeve 6% of portfolio value, against 2% had it stayed unlevered.
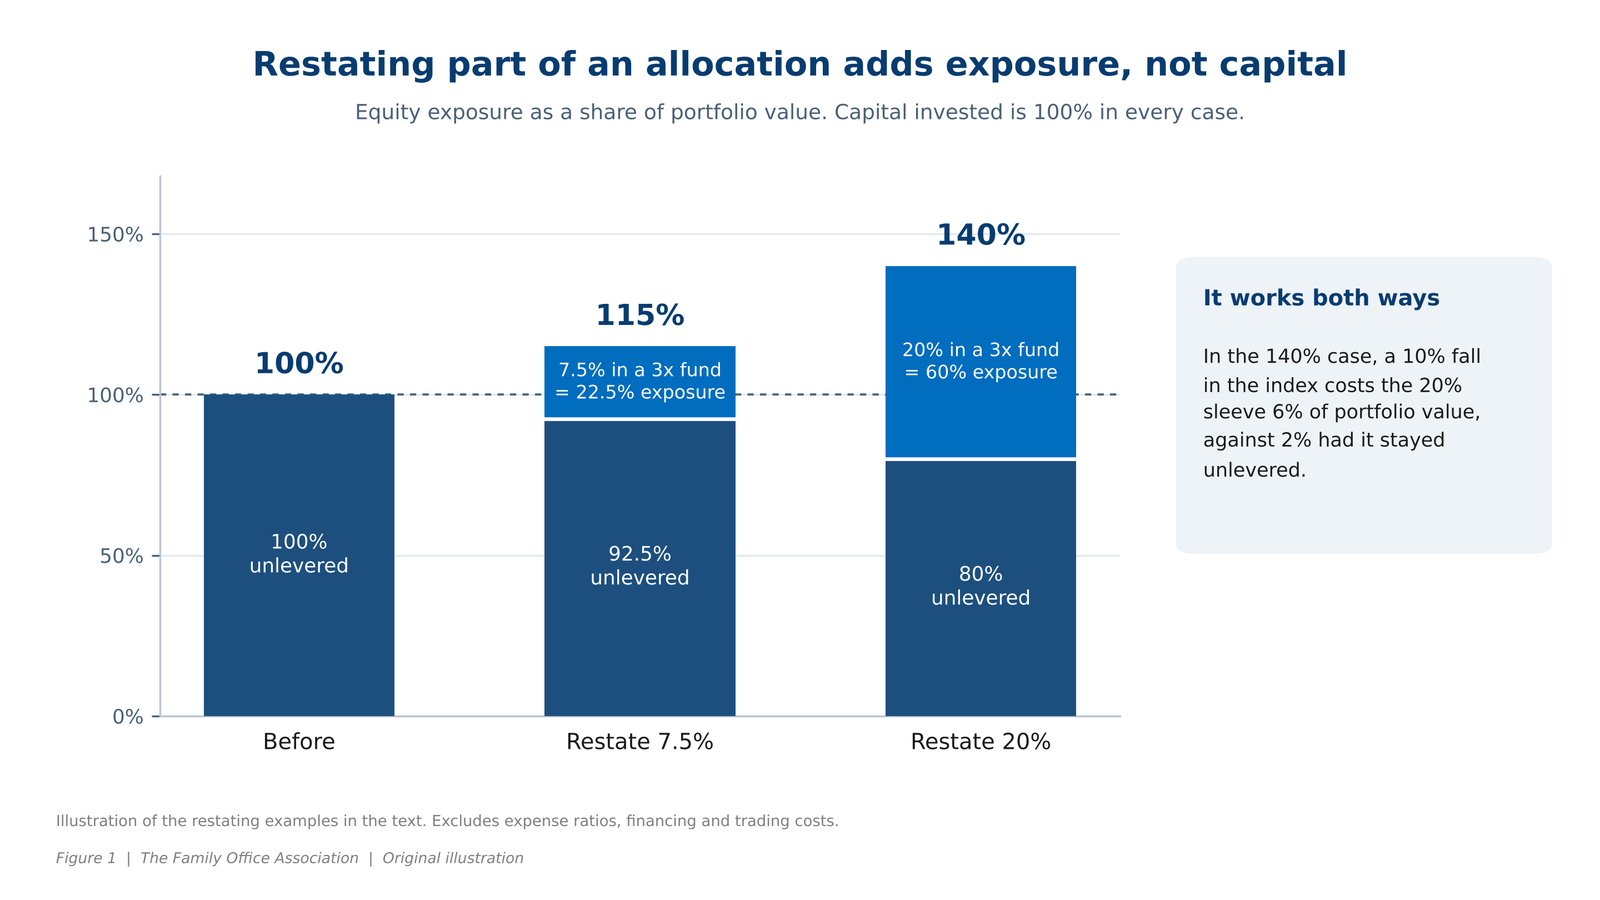
Figure 1. Restating 7.5% or 20% of an unlevered index position into a 3x fund on the same index raises equity exposure to 115% or 140% with no new capital. Original TFOA illustration.
Daily reset and path dependence
Most leveraged ETFs target a multiple of the index’s daily return and rebalance each day to maintain it. Over any period longer than a day, the result depends on the path the index takes, not only on where it ends. Table 1 shows five hypothetical ten-day paths.
Table 1. Ten-day outcomes for a 3x daily-reset fund along hypothetical index paths
| Index path (10 trading days) | Index return | 3x the index return | 3x daily-reset fund | Difference |
|---|---|---|---|---|
| Steady rise (+1% per day) | +10.5% | +31.4% | +34.4% | +3.0 pts |
| Steady decline (−1% per day) | −9.6% | −28.7% | −26.3% | +2.4 pts |
| Choppy, low volatility (±1% alternating) | −0.05% | −0.15% | −0.45% | −0.3 pts |
| Choppy, high volatility (±3% alternating) | −0.45% | −1.35% | −3.98% | −2.6 pts |
| Sharp drop, then recovery (−3% × 4 days, +3% × 6 days) | +5.7% | +17.1% | +15.0% | −2.1 pts |
Hypothetical and illustrative only. Excludes expense ratios, financing costs, and trading costs. Does not represent the performance of any fund or strategy.
Two patterns matter. In trending markets, daily compounding works in the holder’s favor, in either direction: the fund did better than three times the index in both the steady rise and the steady decline. In choppy markets it works against the holder, and the drag grows with volatility. The same roughly flat path costs 0.3 points relative to three times the index at 1% daily moves and 2.6 points at 3% daily moves. The drag scales roughly with the square of volatility, which is why holding period and volatility regime matter more than the leverage ratio itself.
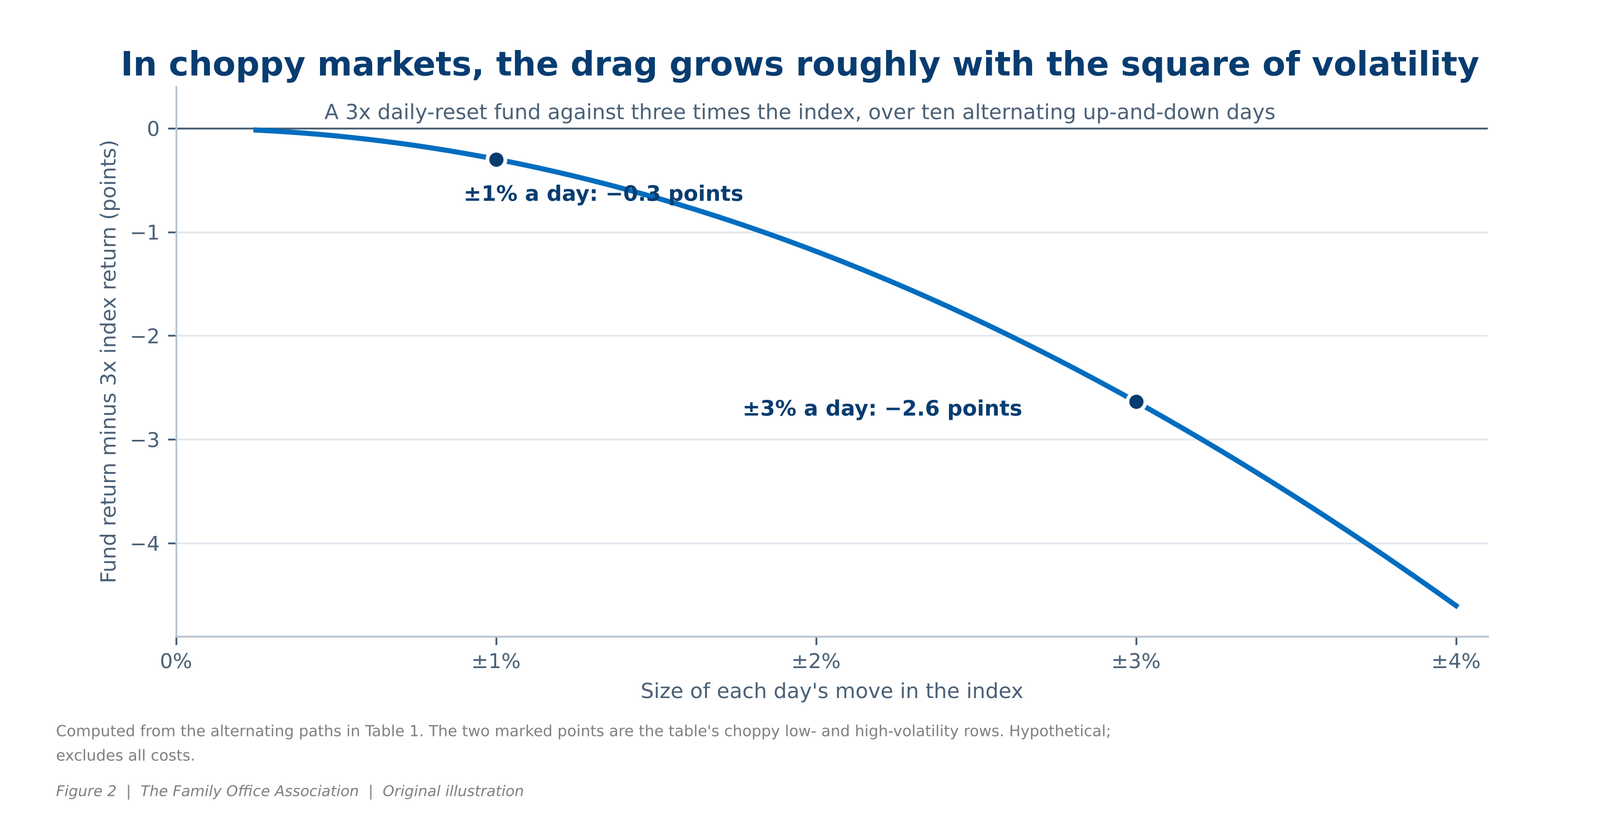
Figure 2. On a flat, alternating path, the cost of the daily reset rises roughly with the square of each day’s move. Computed from the hypothetical paths in Table 1. Original TFOA illustration.
This bears directly on the use case in this paper. Pullbacks are periods of elevated volatility, the conditions in which daily-reset drag is greatest. The last row is closest to that case: a sharp four-day decline followed by a recovery. The fund captured most of the move but trailed three times the index by about two points. A program that uses leveraged ETFs during pullbacks should expect to pay this cost and set position size and holding period accordingly. Monitoring the position does not reduce it.
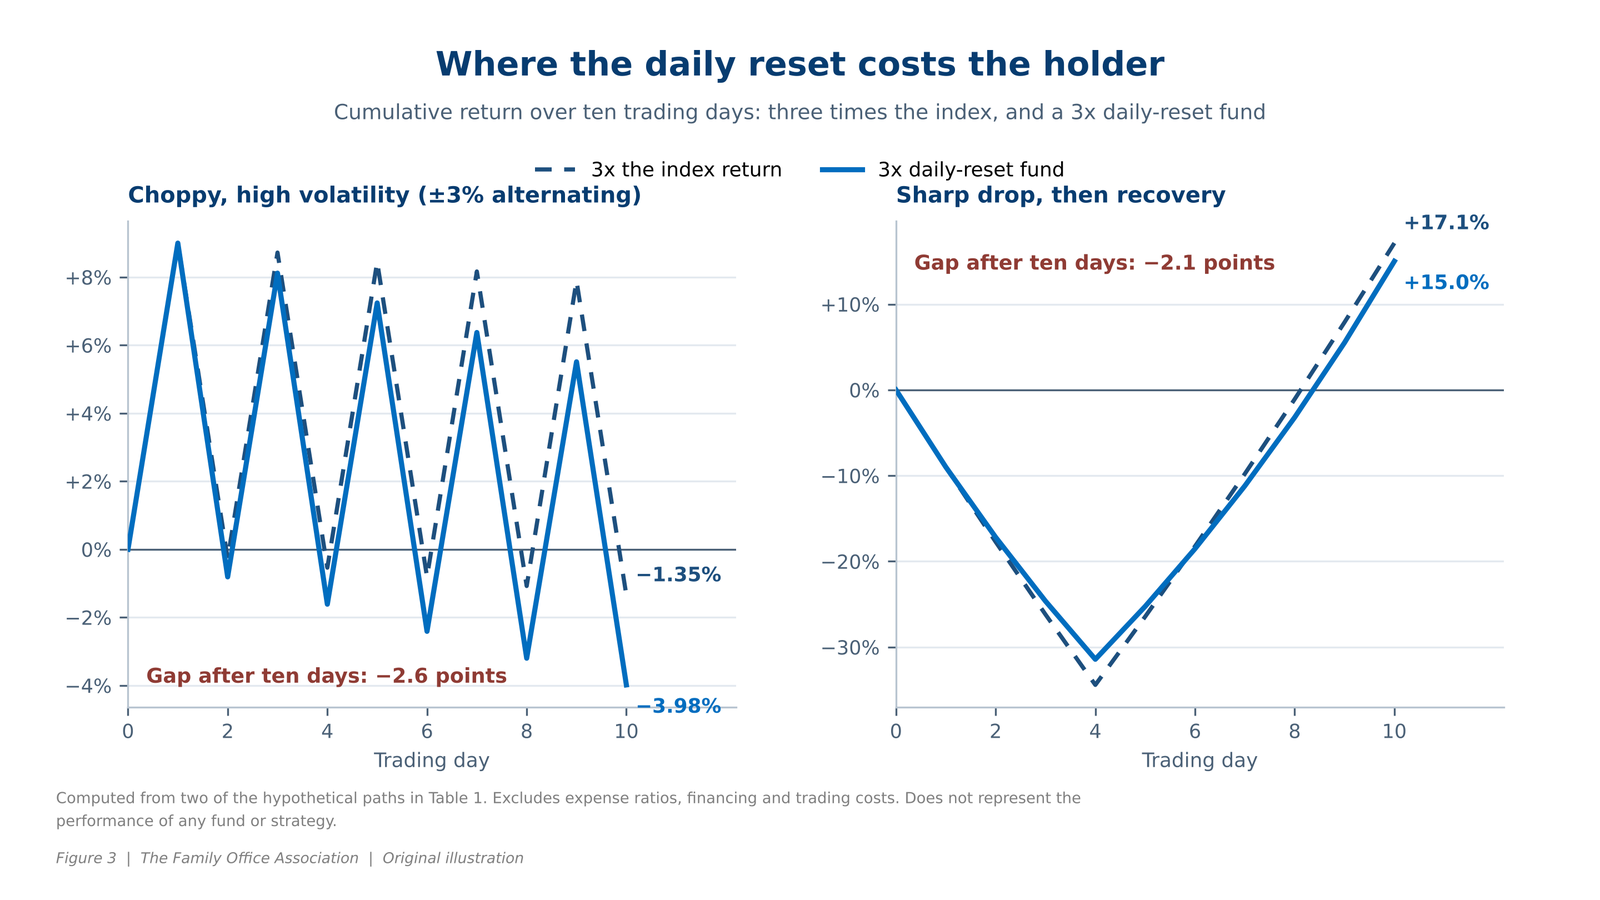
Figure 3. Ten-day paths for a 3x daily-reset fund against three times the index, in the two Table 1 cases closest to a pullback. Original TFOA illustration.
Embedded financing
A leveraged ETF gets most of its exposure through total return swaps and futures, and it pays for that leverage inside its returns rather than as a separate line item. Total cost of ownership has three parts: the disclosed expense ratio typically 0.5–1.0% for broad-index 2x and 3x funds, as of 10/14/2026, the financing embedded in the swaps, broadly a short-term rate plus a spread on the borrowed portion of exposure; and trading costs, including the daily rebalancing. The expense ratio is fixed. The financing component moves with interest rates, as margin does. Vehicles should be compared on all-in cost, not on an expense ratio against a margin rate.
Five Ways to Add Exposure
Leveraged ETFs are one of five common ways to add equity exposure without new cash. Table 2 compares them on the dimensions that tend to decide the question in practice.
Table 2. Implementation alternatives
| Vehicle | Capital tied up | Main cost driver | Infrastructure needed | Account reach | Main drawback |
|---|---|---|---|---|---|
| Index futures | Margin collateral | Financing implied in futures price; roll | Futures account, collateral and roll management | Limited in retirement accounts and on many platforms | Contract size can be coarse for small tranches |
| Margin | None up front; full amount borrowed | Broker margin rate (floating) | Margin agreement | Generally unavailable in retirement accounts | Margin calls can force selling unrelated to the signal |
| Options (calls) | Premium | Implied volatility and time decay | Options approval; strike and expiry management | Restricted in some accounts | Premiums rise with volatility, which is when pullbacks occur |
| Total return swaps | Collateral | Negotiated spread over a floating rate | ISDA documentation, collateral, counterparties | Institutional entities only, in practice | Documentation burden and minimum sizes |
| Leveraged ETFs | One-half or one-third of exposure added | Expense ratio plus embedded swap financing (floating) | Standard brokerage | Broad, though some platforms restrict or require approval | Daily-reset drag in volatile, choppy markets |
Generalized comparison; terms vary by custodian, platform, and fund.
When each vehicle wins
- Futures are usually the cheapest and most precise option for a single large pool of capital that already has the infrastructure. A family office that runs one consolidated institutional account with futures access may find futures more cost-efficient than leveraged ETFs for certain applications.
- Margin is the simplest choice for a single taxable account adding small amounts for short periods, where the risk of a margin call at modest leverage is manageable.
- Options fit when the objective includes a defined maximum loss. A call caps the overlay’s downside at the premium paid, which a leveraged ETF does not.
- Swaps make sense for large, longer-dated exposures where negotiated terms justify the documentation.
- Leveraged ETFs fit when exposure needs to be added in small, predefined increments, held for days or weeks rather than years, and applied identically across entities, custodians, and account types, which is a common situation in family office structures. They also avoid a separate financing relationship.
Where Leveraged ETFs Fit, and Where They Don’t
Appropriate uses
- Tactical overlays with defined entry, sizing, and exit rules, typically held for days to weeks.
- Freeing capital for a known commitment, such as a capital call, by restating part of a core allocation at higher exposure for a defined period.
- Maintaining exposure through a transition: between managers, during a rebalance, or while a liquidity event settles.
Poor fits
- Permanent, unconditional leverage held for years, especially in volatile markets.
- Accounts where no one is assigned to monitor the position.
- Situations where the maximum loss must be known in advance. Options do that; leveraged ETFs do not.
- A substitute for conviction. If the case for more exposure is weak, a more efficient vehicle does not make it stronger.
A PRACTITIONER EXAMPLE
A rules-based pullback overlay
Tamarisk Capital Management’s Defender framework sets equity exposure based on market breadth, momentum, and other measures of market health. When the evidence is healthy, the strategy is fully invested. That creates the capacity problem described above: a meaningful pullback inside a healthy regime leaves no room to add.
The firm added a rules-based tactical overlay. It activates only when two conditions hold at once: a meaningful decline in price, and breadth and other evidence that still classify the regime as healthy. Price weakness alone is not enough. Exposure is added in four predefined tranches, sized from the historical behavior of market drawdowns, up to a maximum of approximately 140%. The incremental exposure is removed under a predefined rule once the drawdown has recovered.
In March 2026, the overlay generated buy signals on March 23 and March 30, adding 15 and 10 percentage points of equity exposure.
After comparing the five vehicles above, the firm chose a broad-index leveraged ETF. Two factors decided it: the same instruction had to apply across taxable, retirement, and third-party platform accounts, and tranches needed finer sizing than futures contracts allowed. The trade-off it accepted is daily-reset drag during the volatile periods when the overlay is active, which it manages through bounded size and a short, rules-defined holding period.
Questions to Answer Before Any Exposure Goes On
The broader lesson is that the vehicle should follow the problem, not the other way around. In practice, that means answering six questions in order.
- What portfolio problem are we solving? A tactical position needs a specific problem. “We want more return” is not one. “We cannot act on opportunities because our liquid capital is committed” is.
- Why leverage, rather than cash or reallocation? If holding cash or selling something else solves the problem at an acceptable cost, leverage may not be needed.
- How much, at most? Maximum exposure should be set in advance, with the office’s other liquidity needs in view. Capital efficiency makes it easy to add exposure; it should not make it easy to add too much.
- Which vehicle? Choose after the problem is defined, on all-in cost, operational requirements, and account eligibility. An office with a different holding period or infrastructure may reasonably reach a different answer.
- Who monitors it, and how often? Daily-reset instruments need a named owner, a review frequency, and a defined set of information to review.
- What takes it off? The exit rule should exist before the position does. Without one, a temporary position can drift into a permanent leveraged allocation, which is a different risk and calls for a different decision.
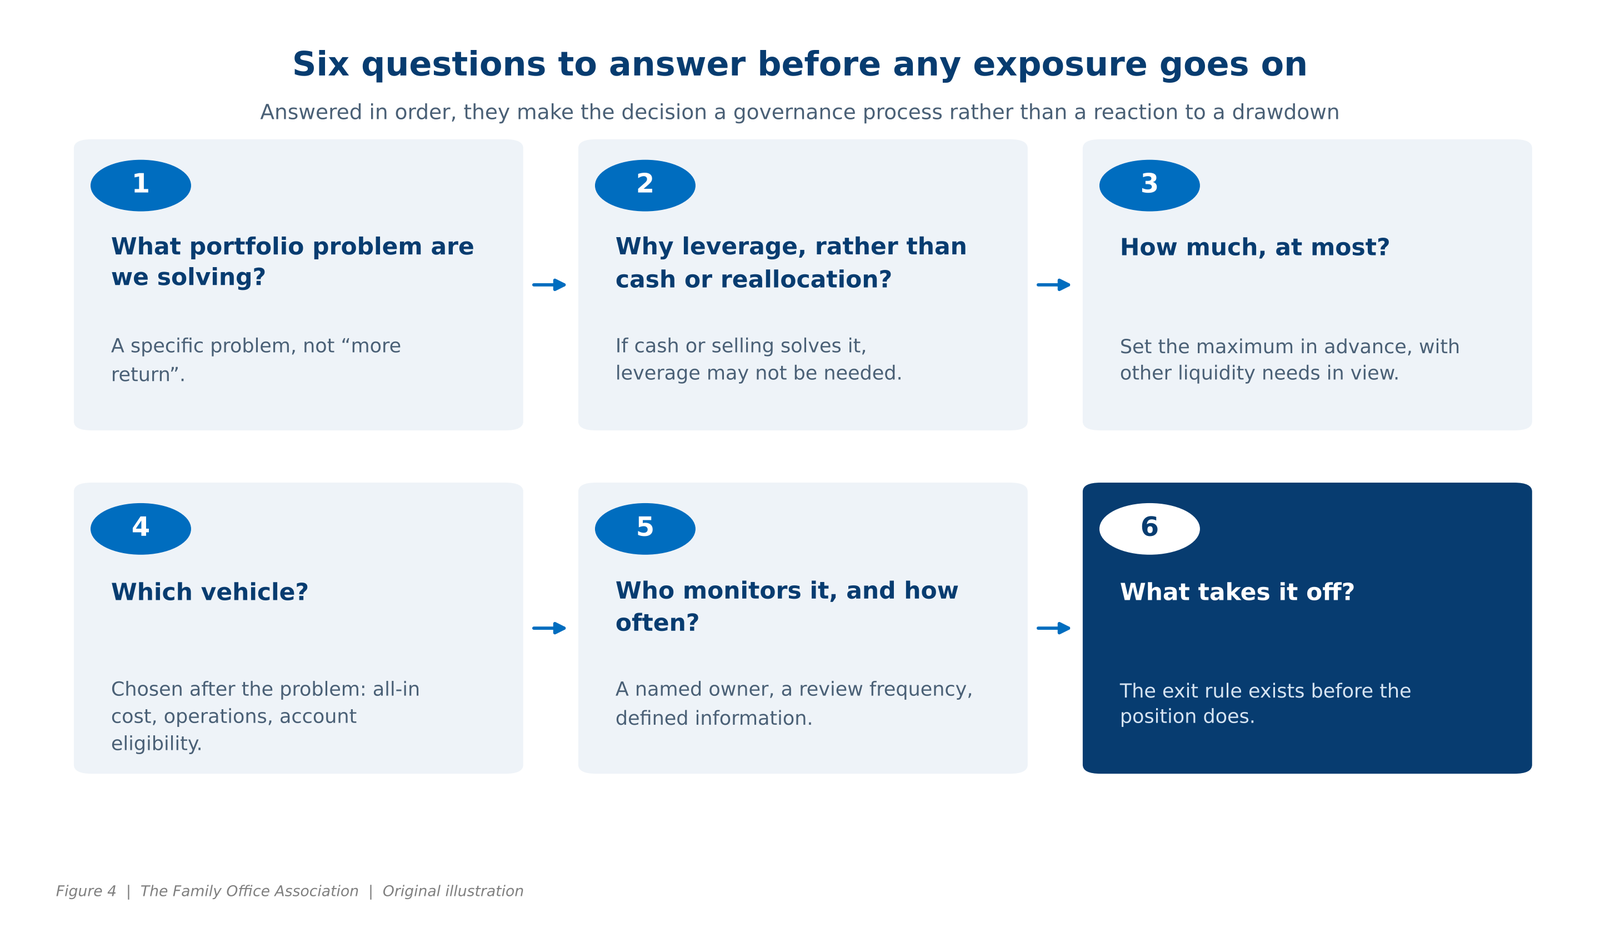
Figure 4. The six questions set out in this paper, in the order the authors recommend answering them. Original TFOA illustration.
Together, these questions amount to a governance process: the objective, sizing, monitoring, and exit are agreed before the exposure goes on, so decisions made during a drawdown follow a framework rather than a mood. Whether leverage belongs in a given portfolio at all is a decision for each family office and its advisers.
Risk Considerations
- Daily-reset drag. Leveraged ETFs are designed around daily objectives, and their returns over longer periods can differ materially from a simple multiple of the index. A pullback overlay is active in exactly the volatile conditions where that difference is largest.
- The pullback may not be temporary. The evidence that a regime is healthy can change after exposure has been added, and losses on the levered position are a multiple of the index decline. Bounded size and incremental additions limit this risk; they do not remove it.
- Liquidity stress can coincide. Capital calls and other demands on liquidity tend to cluster around market stress, so tactical exposure may be largest when liquidity is scarcest.
- Gap risk. Large overnight moves pass through at the full multiple. In theory, a single-day index decline of one-third would eliminate the value of a 3x fund.
- Financing, tax, and platform considerations. Embedded financing costs rise with short-term rates. Leveraged ETFs can make taxable distributions, and treatment should be evaluated for each entity. Some custodians and platforms restrict leveraged ETFs or require additional approval.
Conclusion
Leveraged ETFs answer a specific problem: adding equity exposure when an opportunity appears and liquid capital is already committed. Restating part of an existing allocation at higher exposure raises exposure without new cash, keeps the incremental risk in a single position that can be sized, monitored and sold, and lets the same instruction apply across entities, custodians and account types.
The costs are real. Daily-reset drag is greatest in the volatile, choppy conditions in which a pullback overlay is active; embedded financing moves with short-term rates; and if a pullback proves not to be temporary, losses are a multiple of the index decline. Futures, margin, options and swaps each win in other circumstances. The vehicle should follow the problem, and the objective, sizing, monitoring and exit should be agreed before the exposure goes on. Whether leverage belongs in a given portfolio at all remains a decision for each family office and its advisers.
Bibliography
- Financial Industry Regulatory Authority. (2009, June). Regulatory Notice 09-31: Non-traditional ETFs — FINRA reminds firms of sales practice obligations relating to leveraged and inverse exchange-traded funds.
- StatOasis. S&P 500 declines of 5–10% that did not become a 20% bear market, 1928 to date, computed from daily S&P 500 closes.
- U.S. Securities and Exchange Commission, Office of Investor Education and Advocacy. (2023, August 29). Updated investor bulletin: Leveraged and inverse ETFs.
- Expense ratios cited for broad-index 2x and 3x funds are as of 14 October 2026, as stated by the authors.
- Figures 1 to 4 are original illustrations prepared by The Family Office Association for this paper from the hypothetical examples in the text. Tables 1 and 2 are the authors’.
1 Source: StatOasis, computed from daily S&P 500 closes since 1928. See Bibliography.
Frequently Asked Questions
What is a leveraged ETF?
An exchange-traded fund that delivers a multiple of an index’s daily return per dollar invested, typically two or three times, and rebalances each day to maintain that multiple. It gets most of its exposure through total return swaps and futures and pays for the leverage inside its returns rather than as a separate line item.
How can a family office add equity exposure without new cash?
By restating part of an existing allocation at higher exposure. Selling 7.5% of an unlevered index position and buying 7.5% of a 3x fund on the same index raises equity exposure from 100% to 115% (92.5% × 1 + 7.5% × 3). Restating 20% the same way takes it to 140%. The rest of the portfolio is unchanged, and the incremental exposure sits in a single position that can be sized, monitored and sold.
What is daily-reset drag?
Because the fund rebalances every day, its return over a longer period depends on the path the index takes, not only on where it ends. On the paper’s roughly flat ten-day paths, a 3x fund trailed three times the index by 0.3 points when the index moved 1% a day and by 2.6 points when it moved 3% a day. The drag scales roughly with the square of volatility.
Why does the daily reset matter for a pullback strategy?
Pullbacks are periods of elevated volatility, the conditions in which daily-reset drag is greatest. In the paper’s sharp-drop-then-recovery path the fund captured most of the move but trailed three times the index by about two points. Monitoring the position does not reduce this cost, so position size and holding period have to allow for it.
What does a leveraged ETF actually cost to hold?
Three things: the disclosed expense ratio, typically 0.5–1.0% for broad-index 2x and 3x funds as of 14 October 2026; the financing embedded in the swaps, broadly a short-term rate plus a spread on the borrowed portion of exposure; and trading costs, including the daily rebalancing. The financing component moves with interest rates, so vehicles should be compared on all-in cost.
How do leveraged ETFs compare with futures, margin, options and swaps?
Futures are usually the cheapest and most precise option for a single large pool of capital that already has the infrastructure. Margin is the simplest choice for a single taxable account adding small amounts for short periods. Options fit when the objective includes a defined maximum loss. Swaps make sense for large, longer-dated exposures. Leveraged ETFs fit small, predefined increments held for days or weeks and applied identically across entities, custodians and account types.
When is a leveraged ETF a poor fit?
For permanent, unconditional leverage held for years, especially in volatile markets; in accounts where no one is assigned to monitor the position; where the maximum loss must be known in advance, which options provide and leveraged ETFs do not; and as a substitute for conviction. If the case for more exposure is weak, a more efficient vehicle does not make it stronger.
What should a family office decide before adding exposure?
Six questions, in order: what portfolio problem is being solved; why leverage rather than cash or reallocation; how much exposure at most; which vehicle; who monitors the position and how often; and what takes it off. The exit rule should exist before the position does, or a temporary position can drift into a permanent leveraged allocation.
Frequently Asked Questions
Should a family office use leveraged ETFs?
Only to solve a specific, defined problem, such as wanting to act on a public-market opportunity when liquid capital is already committed. The paper does not argue that leverage belongs in every portfolio or that leveraged ETFs are the right vehicle for every purpose. Whether leverage belongs in a given portfolio at all is a decision for each family office and its advisers.
Are leveraged ETFs suitable for long-term holding?
The paper treats them as a tactical tool, typically held for days to weeks. Because most reset daily, their returns over longer periods can differ materially from a simple multiple of the index, and permanent, unconditional leverage held for years is listed among the poor fits. FINRA and the SEC have both published investor guidance on leveraged and inverse ETFs.
What risks remain however well a leveraged ETF position is managed?
Daily-reset drag in volatile, choppy markets; the chance that a pullback is not temporary, with losses a multiple of the index decline; liquidity stress that coincides with market stress; gap risk, since a single-day index decline of one-third would in theory eliminate the value of a 3x fund; and financing, tax and platform considerations that vary by entity and custodian.
How can a family office apply the same exposure across several entities and custodians?
Leveraged ETFs need only standard brokerage, so the same instruction can apply across taxable, retirement and third-party platform accounts, and tranches can be sized more finely than futures contracts allow. The practitioner example in the paper chose a broad-index leveraged ETF for exactly those two reasons. Some custodians and platforms restrict leveraged ETFs or require additional approval.
About the Authors
Vincent Randazzo, CMT is a Portfolio Manager at Tamarisk Capital Management, founder of ViewRight Advisors, and developer of the Defender framework. His background includes Lowry Research, CFRA, Morgan Stanley, UBS, and Nasdaq, with more than 20 years in institutional technical and breadth-based market analysis.
Ryan Gorman, CFA, CMT, BFA is a Portfolio Manager at Tamarisk Capital Management and Chief Investment Officer of West Michigan Advisors and Tamarisk Research. His work combines fundamental and technical analysis in systematic, rules-based processes.
Marc J. Sharpe, M.A., M.Phil., MBA is a global investment executive and board member with a career spanning family office management, private equity, venture capital, and investment banking. Known for his strategic insight, deep expertise in family office governance, and ability to foster innovation and value creation, Mr. Sharpe has built and led investment platforms that deliver sustainable growth while navigating complex financial and operational challenges. His leadership style emphasizes integrity, continuous improvement, and long-term partnerships that generate significant stakeholder value. Mr. Sharpe is the Founder and Chairman of The Family Office Association, a premier global peer network of single-family offices. Since 2007, he has cultivated a community of senior family office executives and principals representing some of the world’s wealthiest families, promoting education, shared-best practices, and co-investment opportunities. Under his leadership, TFOA has become a trusted forum for collaboration, market insight, and proprietary investment deal flow on a global scale. He also teaches an MBA class on “The Entrepreneurial Family Office” as an Adjunct Professor at Rice University and Southern Methodist University. Mr. Sharpe holds an M.A. from Cambridge University, an M.Phil. from Oxford University, and an MBA from Harvard Business School. Contact: marc@tfoa.me
About TFOA
The Family Office Association (“TFOA”) is a global peer network that serves as the world’s leading single family office community. Our group is for education, networking, selective co-investment, and a resource for single family offices to share ideas, deal flow and best practices. Members are not actively marketing products or services to other members, and no contact information or email lists will ever be shared. Since our founding in 2007, TFOA has led the global single family office community by delivering world-class educational content, unique networking opportunities, and exceptional thought leadership to our highly curated network of the world’s largest and wealthiest families: www.tfoa.info
Important Disclosures
This paper is for informational and educational purposes only and is not an offer or solicitation to buy or sell any security or to adopt any investment strategy. Leveraged ETFs seek a multiple of an index’s daily return; their returns over longer periods can differ significantly from that multiple, and they are not suitable for all investors. Table 1 is hypothetical, excludes all costs, and does not represent the performance of any fund, account, or strategy. References to the March 2026 signals describe a process and are not a representation of results. All investing involves risk, including loss of principal. The figures in this paper are original illustrations prepared by The Family Office Association. They reproduce no third-party artwork.
The Family Office Association (“TFOA”) is a peer network of single family offices. Our community is intended to provide members with educational information and a forum in which to exchange information of mutual interest. TFOA does not participate in the offer, sale or distribution of any securities nor does it provide investment advice. Further, TFOA does not provide tax, legal or financial advice. Materials distributed by TFOA are provided for informational purposes only and shall not be construed to be a recommendation to buy or sell securities or a recommendation to retain the services of any investment adviser or other professional adviser. The identification or listing of products, services, links, or other information does not constitute or imply any warranty, endorsement, guaranty, sponsorship, affiliation, or recommendation by TFOA. Any investment decisions you may make based on any information provided by TFOA is your sole responsibility. The TFOA logo and all related product and service names, designs, and slogans are the trademarks or service marks of The Family Office Association. All other product and service marks on materials provided by TFOA are the trademarks of their respective owners. All of the intellectual property rights of TFOA or its contributors remain the property of TFOA or such contributor, as the case may be, such rights may be protected by United States and international laws and none of such rights are transferred to you as a result of such material appearing on the TFOA web site. The information presented by TFOA has been obtained by TFOA from sources it believes are reliable. However, TFOA does not guarantee the accuracy or completeness of any such information. All such information has been prepared and provided solely for general informational purposes and is not intended as user specific advice.